
Blogs
PW Consulting Forecast: Worldwide Turbocharger Bearing Market to Reach USD 3,075.89 Million by 2032, Growing at a 5.25% CAGR
By pmarketresearch, 2026-08-12
Worldwide Turbocharger Bearing Market: Strategic Imperatives for 2026 — PW Consulting Preview
As PW Consulting releases its latest market study on the Worldwide Turbocharger Bearing Market (base year: 2025; historical window: 2020–2025; forecast period: 2026–2032), this briefing highlights the report’s strategic value for executive decision-making in 2026. The study offers an integrated, commercially actionable view of a market that continues to expand under regulatory pressure, materials volatility and technology-driven product migration. Our forecast shows the market growing at a 5.25% CAGR through 2032, moving from a 2025 base of USD 2,150 Million to a multi-billion-dollar opportunity by 2032. This preview sets out the angles that matter to boardrooms, investment committees and product strategy teams — while reserving the granular segment data for the full report.
Decomposition Product Tester Market
Market Snapshot and What It Means for 2026
The turbocharger bearing market is at an inflection point where mechanical engineering meets emissions policy and supply-chain realism. After several years of steady growth through 2025, the market is projected to expand at a 5.25% compound annual growth rate across 2026–2032. The trajectory reflects continued OEM adoption of advanced bearing technologies (low-friction journal bearings, foil air bearings and hybrid ceramic bearings), growth in downsized and boosted internal combustion platforms, and increasing cross-industry demand from industrial, marine, and power-generation applications.
Metal Enclosures for Electrical Market
For decision-makers planning 2026 investments, two implications stand out: first, the upside is broad but requires targeted capability bets (materials engineering, high-speed dynamics, and thermal resilience); second, cost and supply risks have risen materially, meaning timing and procurement strategy will determine margin outcomes as much as product innovation.
Beating Homogenizer Market
Macro and Industry Dynamics Driving 2026 Choices
-
Regulatory acceleration: Stricter emissions rules — notably Euro 7 in Europe and stage-based heavy-duty engine standards in the U.S. — are increasing demand for turbocharger efficiency improvements. For example, forthcoming heavy-duty standards that target major NOx reductions will force turbocharger system upgrades across fleets, creating a near-term window for bearing upgrades and retrofits.
-
Materials and cost pressure: Supply-side pressures are acute. High-strength alloy steel prices rose ~8% in 2023 and copper inputs for bronze journal bearings experienced notable spikes. These input cost increases compress supplier margins and influence sourcing strategies — making raw material hedging, alternative metallurgy and supplier co-development essential topics for any 2026 procurement plan.
-
Geopolitical and trade considerations: Elevated tariffs and trade frictions have raised cross-border bearing costs and shifted localization calculus for OEMs and Tier 1s. Procurement footprints and nearshoring will be active agenda items in 2026 planning cycles.
-
Technology transitions: Electric turbochargers and e-boost systems change bearing requirements (higher rotational speeds, different thermal profiles), which favors suppliers with foil-air and hybrid-ceramic expertise. Investments in R&D and selective partnerships will determine who captures early-adopter share.
Competitive Landscape — What We Found
The market remains moderately concentrated, with the top three players accounting for roughly half of industry revenues and the top five controlling north of sixty percent — a structure that encourages both competitive specialization and M&A activity. Key incumbent strengths and near-term moves to watch include:
-
Schaeffler Group (Herzogenaurach, Germany) — a recognized leader in journal and foil-air bearings for automotive and commercial turbochargers. Their visible investments in next-generation foil technology position them well for e-turbo applications and OEM co-development programs.
-
SKF AB (Gothenburg, Sweden) — notable for hybrid ceramic and air-foil offerings targeted at high-speed turbo operation. Recent product introductions emphasize durability and lifecycle cost advantages in heavy-duty applications.
-
NTN Corporation and NSK Ltd. (Japan) — both remain strong in conventionally engineered roller and ball bearings, with a focus on low-friction designs for downsized passenger and heavy-duty engines.
-
The Timken Company and RBC Bearings (USA) — known for super-precision and specialty thrust/foil solutions respectively; both are active in niche, high-value segments such as aerospace, marine and power generation where service profiles and qualification timelines favor established suppliers.
-
JTEKT Corporation and Waukesha Bearings — offer depth in needle roller architectures and hydrodynamic journal/tilt-pad bearings that meet industrial turbocharger requirements.
Recent corporate activity (product launches, trade-show reveals, and regional exhibitions) signals a clear pattern: incumbents are accelerating product differentiation through materials science, bearing architecture and system-level partnerships with turbocharger OEMs. Competitive dynamics will center on technical validation cycles, qualification lead times, and aftermarket penetration.
Strategic Imperatives for 2026 Decision-Makers
For executives setting priorities in 2026, our analysis recommends a set of practical, prioritized actions that link technology, procurement and commercial positioning.
-
Prioritize material strategy and supplier co-development: Locking in alloy and copper supply via strategic contracts, co-investing in alternative alloys or coating technologies, and qualifying multi-source suppliers are essential. Without proactive measures, margin erosion from input inflation will continue.
-
Invest selectively in foil-air and ceramic-hybrid capabilities: These technologies carry premium margins in high-speed and e-turbo applications. Allocate a portion of R&D and M&A budgets to accelerate pathway-to-production for foil air-bearing systems or partnerships that shorten qualification timelines with major OEMs.
-
Align product roadmaps to regulatory timelines: Position upgrades and product launches to coincide with Euro 7 and upcoming heavy-duty compliance deadlines. There is a narrow commercialization window where OEMs prioritize validated suppliers; being first to qualify yields outsized share gains.
-
Sharpen aftermarket and service propositions: With many fleets deferring full vehicle replacements, retrofits and turbocharger rebuilds will be a growth pocket. Retain pricing power by bundling bearing upgrades with condition-monitoring and extended-life service agreements.
-
Prepare for M&A and capability-led partnerships: Use M&A selectively to acquire niche capabilities (e.g., foil fabrication, high-temperature ceramics) rather than only volume manufacturing. Smaller bolt-on acquisitions can accelerate time to market more effectively than greenfield development.
-
Scenario-ready procurement: Build upside/downside procurement models that incorporate raw material shock scenarios, tariff paths and supplier outage probabilities. Include pass-through frameworks so commercial teams can respond quickly to cost shocks without long negotiation cycles.
What the PW Consulting Report Delivers (Practical Components)
The full report is built around decision-useful modules designed for commercial, product and procurement teams:
-
Comprehensive market-sizing and growth scenarios — macro-backed forecasts (2026–2032) and sensitivity analyses under multiple regulatory and price-shock pathways.
-
Competitive benchmarking — supplier scorecards that assess technology depth, qualification timelines, manufacturing footprint, and aftermarket capability.
-
Technology and product roadmaps — comparative assessment of journal, ball/roller, foil-air and hybrid architectures, with lifecycle cost and performance tradeoffs.
-
Raw-material and cost-pass-through models — practical tools to quantify margin exposure and to stress-test procurement contracts under commodity price swings and tariff scenarios.
-
Go-to-market playbooks — OEM engagement strategies, qualification-timeline templates, and aftermarket commercialization checklists.
-
M&A and partnership heatmaps — prioritized targets by capability, region and valuation band, together with integration risk assessments.
-
Supply-chain risk map — node-level vulnerabilities, alternative sourcing routes, and recommended contingency mitigations for 12–36 month planning horizons.
Each module pairs quantitative models with executable recommendations — for example, a supplier qualification sequence with estimated lead-time, capex, and validation cost ranges — enabling 2026 program planning to move from strategy to implementation in months, not quarters.
How to Use This Intelligence in 2026
-
Boards: Use the forecast scenarios and concentration metrics to validate capital allocation, M&A appetite and risk tolerance for near-term deals.
-
Product leaders: Prioritize R&D sprints on foil-air and hybrid materials; secure OEM pilot programs timed against regulatory milestones.
-
Procurement: Execute layered supplier contracts with hedging and qualification contingencies informed by our raw-material sensitivity model.
-
Commercial teams: Rework customer propositions to include retrofit pathways and long-term service agreements that capture aftermarket recurring revenue.
Closing — Why This Matters Now
The turbocharger bearing market presents a classic strategic dilemma: expanding demand set against heightened input volatility and compressed qualification timetables. The top-three players already account for roughly half of industry revenue, and the top-five for well over sixty percent, which creates both barriers and opportunities for entrants and incumbents. For companies plotting 2026 moves, success will depend on integrating materials strategy, focused capability investments and nimble commercial execution.
PW Consulting’s report converts these high-level truths into operational plans: prioritised R&D investments, procurement hedges, deal targets and go-to-market sequences that can be actioned in 2026. The sections above outline the strategic stakes and practical levers; the full report contains the underlying models, segmented forecasts, and supplier-level analysis needed to execute with confidence.
Next Steps
To access the complete market models, our supplier scorecards, and the full set of scenario outputs — including granular segment-level forecasts and the proprietary matrices used to generate the 5.25% CAGR outlook — please consult the PW Consulting report landing page. The full dataset and playbooks are designed to be directly deployable into 2026 planning cycles and will support rapid decision-making across commercial, product and procurement teams.
For detailed analysis of this topic, please visit the official page: Worldwide Turbocharger Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pro Microphone Market Reaches USD 3,215.4 Million in 2025, Forecast to Grow at a 6.01% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Pro Microphone Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Professional Microphone Market delivers the evidence-based intelligence executives need to make confident 2026 decisions. Built on a 2020–2025 historical foundation and a 2026–2032 forecasting framework, the report quantifies the market trajectory and converts that insight into operational playbooks for product, procurement, channel, and M&A leaders. In summary: the professional microphone market reached USD 3,215.4 Million in 2025 and is forecast to expand at a 6.01% compound annual growth rate to roughly USD 4,834.8 Million by 2032. This growth creates clear opportunities — and specific risks — that require targeted strategic responses in 2026.
Portable Constant Temperature Amplification Nucleic Acid Analyzer Market
Why this report matters now
-
Decision alignment for 2026 budget cycles — deploy capital where growth and margin expansion intersect, and avoid areas where price compression or supply risk will erode returns.
Worldwide Asphalt Rollers Market -
Mitigating supply-chain stress — executable sourcing and inventory strategies that address rare-earth concentration, extended component lead times, and tariff exposure.
Worldwide Stainless Steel Sanitary Ware Market -
Commercial acceleration — playbooks for OEMs, pro audio brands, and channel partners to capture demand generated by streaming, podcasting, corporate AV upgrades, and the rebound in live performance spend.
-
M&A and partnership screening — a prioritized list of capability gaps and target archetypes to accelerate time-to-market for DSP-enabled, networked, and miniaturized product lines.
What the report contains — practical, actionable modules
-
Market sizing and validated forecasts (2020–2025 historical; 2026–2032 projection) with scenario variants to stress-test macro shocks.
-
Price and margin archetypes across product classes and channels, with guidance on where premiumization yields the best incremental EBITDA.
-
Supply-chain risk matrix — rare-earth dependence, component lead-time modeling, tariff pass-through scenarios, and a supplier-diversification playbook.
-
Competitive intelligence dossiers — capability maps, recent product moves, and tactical responses for incumbents and challengers.
-
Go-to-market blueprints — retailer and pro-channel strategies, enterprise tender playbooks, and direct-to-creator engagement models.
-
M&A screening toolkits — value-creation levers, integration risks, and prioritized target archetypes for bolt-on acquisitions.
-
Regulatory and sustainability compliance checklist (including RoHS and other EEE restrictions) and implications for product redesign and labeling.
Market snapshot & concentration dynamics
The market’s mid-decade size and projected trajectory signal a resilient, mid-single-digit expansion driven by multiple secular trends: professional content creation, broadcast technology refresh cycles, and recovery in live events and corporate AV investments. Market concentration is meaningful but not prohibitive — the top three firms account for a material share of sales while the top five consolidate a clear majority of the market’s leading brands. In practice, this structure creates both defendable franchises for incumbents and whitespace opportunities for nimble challengers that combine hardware with software and services.
Competitive landscape — capabilities and strategic positioning
Our analysis profiles the full spectrum of industry participants, from global incumbents to specialist boutique makers. Key strategic takeaways:
-
Heritage live-sound and wireless strength: Established names with deep pro-audio distribution and legacy catalogue advantage continue to defend lead positions in live sound and installed applications through brand trust and channel density.
-
Studio and broadcast premium: High-end manufacturers focused on studio condensers and precision measurement equipment retain margin advantage through product differentiation and strong placement in professional facilities.
-
Creator and entry-pro disruption: Newer entrants and value brands have successfully grown share among podcasters, streamers, and small studios by offering high performance at aggressive price-to-value ratios, often bundled with software and ecosystem features.
-
Networked audio and DSP convergence: Vendors launching Dante-enabled boundary microphones, integrated DSP, and low-noise condenser upgrades represent the fastest route to higher ASPs and recurring revenue through software services and firmware-enabled features.
Recent product activity reinforces these themes: companies across the spectrum have introduced ultra-low-noise condensers, integrated DSP/wireless systems, and Dante-enabled conferencing boundary mics — moves that validate the strategic importance of low self-noise, network interoperability, and wireless robustness in product roadmaps.
Industry headwinds and tailwinds
-
Raw materials and supplier concentration — a significant share of refined rare earth output is concentrated geographically, and the average price of key rare-earth oxides has experienced upward pressure. For dynamic microphone magnets and related components, this translates into input-cost volatility that can compress margins or force price increases if not proactively managed.
-
Component lead times — capacitors, ICs, and other electronic parts saw extended lead times throughout recent quarters; product planning must assume multi-quarter procurement windows and identify alternative form, fit, and function suppliers.
-
Trade-policy friction — tariffs on certain imported microphones can materially alter landed-cost economics for firms with concentrated manufacturing footprints. Nearshoring or tariff-classification strategies are no longer optional for cost-sensitive product lines.
-
Regulatory compliance — directives restricting hazardous substances continue to affect design, supplier selection, and certification timelines. Compliance-driven redesigns can create both cost pressure and a barrier to entry for smaller suppliers.
-
Demand-side accelerants — streaming, podcasting, esports, and corporate AV digitization are persistent growth vectors that reward products designed for ease-of-use, integrated software, and platform compatibility.
2026 Strategic playbook — prioritized moves for executive teams
PW Consulting’s recommended actions are organized by horizon and impact to help senior teams translate market signals into measurable outcomes in 2026.
-
Short term (0–12 months): secure critical components via multi-source agreements, hedge exposure to rare-earth price moves, and review tariff mitigation through alternative manufacturing locations or HTS reclassification strategies. Implement inventory buffers for long-lead components tied to critical SKUs.
-
Medium term (12–24 months): accelerate product lines that embed DSP and network connectivity (e.g., Dante, AES67), and launch feature tiers that enable subscription-based firmware or cloud services. Prioritize compliance-ready designs to reduce time-to-market risk for regulated geographies.
-
Strategic deals and M&A: target technical niche plays (miniature lavaliers, measurement mics, or DSP-software specialists) that can be integrated to expand margin pools and shorten time to market for new integrated offerings. Use our scoring model to evaluate five archetypes that deliver the best probability-adjusted returns.
-
Commercial and channel: bifurcate GTM by buyer segment — defend pro-channel relationships with service-level agreements and exclusive SKUs, while scaling direct-to-creator channels through bundled software, content partnerships, and influencer-driven trials.
-
Operational excellence: institute supplier KPIs tied to lead time and quality, and create a joint risk register with top suppliers. Conduct a tariff and tax optimization review to quantify landed-cost improvements from reshoring or contract manufacturing shifts.
How to use the full report
This press briefing highlights the macro trajectory, competitive dynamics, and operational levers that shape 2026 choices. The full PW Consulting report contains the proprietary datasets, scenario-model workbooks, and executable templates you need to implement the recommendations above — including downloadable procurement playbooks, M&A screening sheets, and regional market tables. For pricing-by-product, channel-specific margin models, and the full segmentation dataset, please consult the complete report on PW Consulting’s website or contact our industry team for a tailored briefing.
Final note — where to focus in 2026
As the professional microphone market grows into the mid-2030s, the winners will be those who combine differentiated acoustical IP and product design with modern supply-chain resilience and software-enabled revenue models. 2026 is the inflection year for many firms: moves made now on sourcing, platform partnerships, and product-tier strategy will determine who captures the higher-margin segments of the market and who is left to compete solely on price. PW Consulting’s Worldwide Pro Microphone Market report is designed to fast-track those decisions with validated data and playbooks you can act on immediately.
For detailed analysis of this topic, please visit the official page: Worldwide Pro Microphone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Heavy Truck Battery Swap Stations Market Poised to Grow at a 21% CAGR
By pmarketresearch, 2026-08-12
PW Consulting Releases Strategic Brief: Worldwide Heavy Truck Battery Swap Stations Market — A 2026 Decision-Maker’s Guide
PW Consulting today publishes an executive briefing that previews our forthcoming in-depth market research report on the Worldwide Heavy Truck Battery Swap Stations Market. Built on a 2025 base year and a seven-year forecast horizon (2026–2032), the report synthesizes five years of historical market movement (2020–2025) and projects an accelerated adoption curve with a compound annual growth rate (CAGR) of 21.0% through 2032. The market—measured in USD millions—grew from the low hundreds in 2020 to USD 1,250 million in 2025 and is forecast to approach USD 4,747 million by 2032. For infrastructure owners, OEMs, fleet operators and energy partners preparing strategic moves in 2026, this briefing highlights the decision levers that matter while directing readers to the full report for proprietary segmentation and financial models.
Worldwide Silicon Friction Resistant Bronze Alloys Market
Why 2026 Is a Pivotal Year
-
Transition from pilots to rollouts: The market dynamics observed between 2020 and 2025 show a rapid transition from proof-of-concept deployments to early commercial networks. Our forecast quantifies the scale-up and identifies the inflection points where capex commitments and operational models will determine winners and losers.
Christmas Travel Market -
Standardization and interoperability: Regulatory and industry standard progress is reducing technical risk. Notably, recent group standards define upper bounds on system voltage and swap-time targets for heavy trucks—benchmarks that materially affect station design, battery form factor strategies and interoperability frameworks.
Smart Wearable Button Battery Market -
Market concentration: The heavy truck swap-station market is already meaningfully concentrated. Our analysis estimates that the top three firms command roughly two-thirds of the market, while the top five extend control to well over three-quarters. This concentration has strategic implications for new entrants and for potential partnership or consolidation plays.
Key Strategic Imperatives for 2026 Decision-Makers
-
Choose your route to scale: Build, partner or license. Our report provides a framework for evaluating full-ownership networks versus fleet-dedicated alliances and asset-light models. The right choice depends on balance-sheet capacity, access to site footprints, and the ability to control interoperability standards.
-
Optimize CAPEX/OPEX trade-offs under evolving standards: Station automation levels, battery handling systems and grid-upgrade strategies materially change lifecycle economics. We map out scenarios that link automation investments to swap throughput, downtime risk and technician requirements.
-
Site and grid triage for rollouts: A pragmatic deployment roadmap—prioritizing corridors, freight hubs and integrated fleet depots—will determine early cash-flow profiles. Grid capacity is a binding constraint for high-throughput stations; specifications for grid connection should be part of any site due diligence.
-
Commercial models and fleet contracts: Capturing recurring revenue via subscription, pay-per-swap or hybrid models requires coordinated battery ownership and warranty strategies. Our commercial model templates show pricing sensitivities and scenario-based payback timelines.
-
Regulatory capture and incentive timing: Where subsidy windows and local infrastructure programs exist, timing market entry to capture incentive support materially improves returns. Regulatory engagement and compliance with emerging technical standards will be a gating item for cross-operator compatibility.
Competitive Landscape: Who’s Shaping the Market Now
-
CATL (Ningde, China) — A major systems integrator whose heavy-duty swap network demonstrates end-to-end standardization across stations and battery packs; engineering focus is on standardized interfaces and fast-swap flows designed for very high-capacity batteries and short turnaround times. Recent field commissioning of a standardized heavy-duty station underscores CATL’s intent to set operational benchmarks.
-
Farizon Auto (Hangzhou, China) — Leverages OEM convergence with modular swap architectures optimized for specific logistics vehicle families. Its early network deployments show the advantages of OEM-aligned swap formats and tightly integrated vehicle-station ecosystems.
-
TGOOD (Shenzhen, China) — Positions as a turnkey provider for operators, combining station hardware, control software and maintenance operations; commercial deployments across multiple provinces illustrate its channel and project-execution capabilities.
-
Aulton New Energy (Wuxi, China) — Translates mass-transit swap expertise to heavy trucks, offering automated battery handling and station-level automation; its approach highlights the transferability of technology from buses to heavy-duty truck applications.
These vendors illustrate the strategic archetypes in the market—standard-setters, OEM-backed integrators, turnkey station suppliers and technology-transfer specialists. For established players and newcomers alike, the competitive task is less about raw capability and more about network economics, partner ecosystems and standards alignment.
Industry Dynamics and Operational Constraints
-
Technical standards: Recent government-endorsed standards set performance targets (including upper voltage limits and swap-time ceilings) that influence battery architecture and station automation investments. Compliance reduces fragmentation risk but raises the bar for engineering tolerances.
-
Grid and infrastructure requirements: High-throughput stations require robust grid connections and energy management systems. Grid reinforcement and local distribution coordination are frequently on the critical path for deployment timelines.
-
Component cost trajectories and supply chain: Large-format LFP packs and high-capacity swap batteries remain a major cost element. Economies of scale and supply chain localization are the primary levers to reduce pack costs over time.
-
Public policy and local incentives: Many jurisdictions are offering targeted incentives to accelerate rollout. Capturing these incentives requires nimble project execution and adherence to eligibility rules, which vary by location and program.
What the PW Consulting Report Contains (Actionable Modules)
Our full report is organized to support immediate 2026 action planning. Key components include:
-
Market sizing and forecasting models (base year 2025) with downloadable, scenario-driven financial models that allow users to test sensitivity to throughput, pricing and capex assumptions.
-
Deployment playbooks detailing site selection criteria, phasing strategies, and rollout sequencing optimized for commercial and fleet-first approaches.
-
Capex and opex benchmarking across automation levels and station formats, with cost drivers and risk levers identified for procurement teams.
-
Regulatory and standards compendium outlining technical requirements, certification pathways and implications for interoperability.
-
Competitive matrix and vendor scorecards that evaluate technology fit, execution capacity, partnership openness and potential M&A targets.
-
Commercial templates—for swap pricing, subscription structures, fleet contracts and revenue-sharing agreements—ready to be adapted to specific markets.
-
Investment case studies and scenario-based IRR/payback analyses under multiple market adoption curves.
-
Risk register and mitigation playbook covering technical, commercial, regulatory and grid-related risks.
How to Use This Intelligence in 2026
-
For OEMs: Use the report to decide whether to standardize battery interfaces, pursue owner-operated stations, or align with third-party networks to protect long-term vehicle value and customer proposition.
-
For fleet operators: Evaluate whether to co-invest in fleet-dedicated stations or partner with public networks. Our sensitivity models help determine the threshold utilization rates at which each option becomes preferable.
-
For energy and infrastructure investors: Prioritize investments in grid-enabled sites and energy-storage co-locations that improve station economics and deliver ancillary grid services.
-
For station operators and system suppliers: Benchmark automation choices, O&M staffing models and spare-parts strategies to reduce downtime and improve throughput.
Why PW Consulting’s Analysis Is Distinctive
-
Integrated perspective: We combine market-sizing rigour with engineering realism and commercial templates—bridging the gap between strategic forecasts and executable roll-out plans.
-
Scenario-driven tools: Instead of a single forecast narrative, subscribers receive modular financial models that stress-test business cases under alternative adoption trajectories.
-
Vendor-agnostic operational playbooks: Our recommendations are oriented toward pragmatic decision-making—what to build, when to partner, and how to protect optionality as standards and technology evolve.
Next Steps and Accessing the Full Report
This briefing is a preview designed to equip senior leaders with the strategic framing necessary for 2026 decision-making. The full PW Consulting report contains the detailed segmentation, proprietary unit-cost models, and granular regional analyses that underpin the conclusions summarized here. Organizations seeking to translate this intelligence into an actionable 12–24 month plan can commission a tailored advisory engagement, access the full report, or request the downloadable financial model.
To request the complete report or to discuss a bespoke advisory engagement, please contact PW Consulting’s Heavy Transportation and Energy Infrastructure practice. Our team will help you rapidly convert market insight into investment-grade plans.
PW Consulting — translating market foresight into executable strategy for the heavy-duty electrification era.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy Truck Battery Swap Stations Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Image Signal Processor Market to Hit USD 8.8 Billion by 2032, Growing at a 13.01% CAGR—Asia Pacific Leads with USD 1.79B in 2025
By pmarketresearch, 2026-08-12
Worldwide Automotive Image Signal Processor Market: Strategic Insights for 2026 Decision-Makers
PW Consulting — Official Release (based on our 2025 base year study)
The market for automotive Image Signal Processors (ISPs) has shifted from a niche enabling technology to a central pillar of vehicle perception, occupant monitoring, and safety-systems architectures. Our new Worldwide Automotive Image Signal Processor Market report — using 2025 as the base year and projecting across a 2026–2032 forecast horizon — synthesizes technology roadmaps, supplier economics, regulatory pressure points, and program-level demand signals to give senior executives the action-oriented intelligence needed to make confident decisions in 2026.
Research Cell Analyzers Market
Why this market matters in 2026
ISPs are no longer “image tuning” peripherals. They are compute elements that determine how camera-based sensors translate photons into reliable inputs for ADAS, automated driving stacks, and in-cabin systems. The sector is expanding rapidly: our market model shows growth from roughly USD 2.15 billion in 2020 to USD 3.74 billion in 2025, with projections that place the market near USD 8.80 billion by 2032 — an implied compound annual growth rate of 13.01% over the forecast period. Concentration is meaningful: the top three suppliers control a clear majority of market value, and the top five extend that dominance further, creating both challenges and windows of opportunity for new entrants and OEM procurement strategies.
Human Skin Equivalent Market
What the PW Consulting report delivers (practical, decision-ready content)
- Market-sizing and validated demand model: a bottom-up revenue model calibrated to automotive program cadences and camera content-per-vehicle trends across light-vehicle platforms (global forecast 2026–2032).
- Technology deep dives: comparative analysis of integrated vs. standalone ISP architectures; HDR and multi-exposure pipelines; AI/NPU integration trends; and the emerging role of MIPI A-PHY and sensor-ISP co-design for high-bandwidth applications.
- Supplier landscaping and heat maps: competitive positioning, go-to-market motions, design-win velocity, and a proprietary supplier-readiness index for ADAS and in-cabin use cases.
- Regulatory and supply-risk assessment: scenarios that quantify the potential impact of tariffs, raw-material constraints, and lead-time variability on program-level BOMs and supplier selection.
- Strategic playbooks: templates for sourcing negotiations, tiered-supplier strategies, modularization vs. integration decisions, and M&A/partnership screening criteria tailored to 2026 objectives.
- Executive-ready dashboards: KPIs and trigger points for procurement, R&D prioritization, and product roadmap alignment — designed to be used in quarterly board discussions.
How the findings change 2026 decision-making — three priority implications
- Architectural posture matters: ISPs are becoming design choices with systems-level consequences. Choosing integrated SoCs vs. standalone ISPs affects supplier leverage, update cadence for algorithms, and functional-safety pathways. Our scenario analysis quantifies the trade-offs for both near-term cost and medium-term TCO.
- Safety and certification will drive supplier selection: With recent certifications and ASIL compliance progress, functional-safety readiness is now a procurement filter, not an afterthought. Programs that lock into suppliers without certified IP risk costly redesigns as OEMs move to higher ADAS levels.
- Supply-chain and trade policy risk is real: New trade measures and extended semiconductor lead times materially change the risk profile of single-source strategies. The report provides probability-weighted impact analyses that map potential tariff scenarios to supplier cost uplifts and schedule slippage.
Competitive landscape — who matters and why
The ISP ecosystem blends pure-play image specialists, broad-based semiconductor houses, and system-SoC providers. PW Consulting profiles the active competitive set and assesses strategic levers for each player class:
Worldwide Wind Turbine Maintenance, Repair & Overhaul (MRO) Market
- onsemi (Semiconductor Components Industries, LLC) — a supplier with automotive-dedicated ISP co-processors optimized for HDR sensors; their automotive focus and sensor partnerships make them a compelling partner for surround-view and ADAS programs that emphasize low-latency pipelines.
- OmniVision Technologies — offers a portfolio of automotive ISPs and companion processors with integrated NPUs and advanced HDR/LED-flicker mitigation; suited to customers prioritizing sensor-to-perception integration and OEMs seeking compact camera-module stacks.
- STMicroelectronics — integrates ISP capabilities within broader sensor and vision portfolios, appealing to Tier-1s aiming to simplify system integration and accelerate time-to-market for zonal architectures.
- Texas Instruments — leverages broad analog-to-digital and vision ecosystems, serving programs where mixed-signal integration and robust automotive-grade supply are primary concerns.
- NXP Semiconductors — positions ISP functionality within platform processors (e.g., i.MX derivatives), attractive when OEMs or Tier-1s seek consolidated compute platforms with software ecosystems.
- Renesas Electronics — focuses on vision processors and ISP capability tuned to automotive-grade requirements, especially where integration with microcontroller domains is a program priority.
- Nextchip — differentiates through ADAS/SoC offerings targeted at L2+ to L3 deployments, appealing to customers across markets looking for performance at scale.
- VeriSilicon — supplies automotive ISP IP with high throughput and a growing functional-safety pedigree, making it a go-to for companies seeking licensable ISP cores with ISO 26262 certifications.
- Sony Semiconductor Solutions — as a sensor leader, Sony’s moves (including the introduction of sensor interfaces like MIPI A-PHY) influence ISP requirements and camera-module economics; pairing Sony sensors with tuned ISP pipelines yields performance differentiation.
- Ambarella — brings high-performance vision SoCs with advanced ISP stacks for compute-heavy ADAS applications, attractive where local perception and compression are both required.
- Qualcomm — integrates ISP capability into vehicle platforms and infotainment/AD stacks, offering software ecosystems and long-tail support beneficial for connected-vehicle strategies.
Recent developments underscore dynamic competitive shifts: Sony’s IMX828 (announced Oct 2025) introduced a MIPI A-PHY-enabled sensor with extended HDR capability; VeriSilicon achieved ISO 26262 certification for a second-generation ISP IP (Feb 2026); and specialist IP upgrades from logicBRICKS enhanced RGB-IR processing in 2025. Each event alters technical ceilings and procurement considerations for OEMs and Tier-1s.
Risk vectors and regulatory dynamics to watch in 2026
- Trade policy and tariffs: Recent U.S. measures imposing duties on certain advanced computing chips and ongoing Section 232 negotiations introduce near-term price and sourcing uncertainty. Our report models tariff pass-through scenarios and recommended sourcing hedges.
- Supply-chain strain: Automotive semiconductor lead times lengthened materially in late 2025; the report models how two-week shifts in lead time cascade into program buffer needs and just-in-time inventory policies.
- Functional safety and certification: With IP vendors and partners reaching ASIL-B/D milestones, OEMs must elevate certification timelines into supplier selection criteria to avoid late-stage rework.
- Technology obsolescence and software risk: Rapid innovation in NPUs, HDR pipelines, and interface standards (e.g., MIPI A-PHY) means hardware choices lock software constraints; our scenario planning quantifies upgrade costs across multiple product lifecycles.
How to use this intelligence in 2026 — tactical next steps for leaders
- Procurement: Re-calibrate supplier scorecards to include functional-safety readiness, A-PHY interface support, and roadmap alignment for AI-enabled pipelines; activate dual-sourcing where tariff exposure or lead-time sensitivity is high.
- R&D and product planning: Prioritize sensor-ISP co-development in projects targeting high-HDR or multi-sensor perception; budget for incremental software headroom to exploit on-chip NPUs.
- M&A and partnerships: Use our supplier-readiness index and thermal maps to shortlist acquisition or JV targets that close capability gaps (e.g., certified ISP IP, high-throughput pipelines, or sensor integration competencies).
- Risk mitigation: Implement trigger-based inventory buffers tied to lead-time and tariff scenarios modeled in the report; negotiate price-protection clauses with strategic suppliers.
- Regulatory preparedness: Integrate ISO 26262 milestones into program Gantt charts and require proof points for ASIL compliance in early design phases.
About the market model and confidence in our projections
Our forecast combines demand-side indicators (vehicle production, camera content per vehicle, ADAS penetration curves) with supply-side modelling (supplier capacity, wafer constraints, and BOM change dynamics). Scenario sensitivity testing around tariffs, lead-time shocks, and accelerated ADAS adoption informs our central 13.01% CAGR projection and the pathway to approximately USD 8.80 billion by 2032. The model is designed for iterative use — teams can re-run scenarios with program-specific inputs using templates included with the report.
Next steps — access and engagement
This release is an executive preview designed to highlight the strategic value of the full report. The complete study contains granular, program-level intelligence (including supplier matrices, build-cost frameworks, and downloadable model files) that we intentionally withhold here to protect the actionable core of the research. PW Consulting offers tailored briefings, workshop sessions to map these findings into client roadmaps, and customized scenario runs for procurement and M&A teams.
For procurement leaders, systems architects, and corporate strategists preparing 2026 budgets and roadmap commitments, the report provides the decision-ready analytics needed to balance performance, safety, and supply security in an ISP-driven world. To request the full report or schedule a briefing, please visit the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Image Signal Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide DC Power Supplies & Electronic Power Loads Market to Expand from USD 3,845.5 Million in 2025 to USD 5,944.5 Million by 2032 at a 6.42% CAGR
By pmarketresearch, 2026-08-12
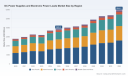
Worldwide DC Power Supplies and Electronic Power Loads Market: Strategic Insights for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market intelligence on Worldwide DC Power Supplies and Electronic Power Loads positions senior executives to make higher-confidence decisions in 2026. Our analysis shows the market continuing its steady expansion from a 2025 base of approximately USD 3,845.5 million to a materially larger opportunity by the end of the 2026–2032 forecast window — driven by an underlying compound annual growth rate of 6.42%. That macro trajectory masks faster pockets of innovation (high-voltage, bidirectional/regenerative systems, SiC/GaN-enabled designs) and uneven supply-side pressures that will define winners and laggards over the next 18–36 months.
Epoxy Cast Dry-type Transformer (≤35KV) Market
Why this report matters in 2026
- Practical timing: 2026 is a pivot year — product roadmaps, capacity investment, and procurement strategies set now will determine cost and lead-time performance through the next hardware cycle.
- Risk-to-reward squeeze: Component inflation, raw material export controls, and regulatory actions are compressing margins and complicating sourcing while demand for higher-efficiency power electronics continues to rise.
- Decision utility: The research converts market-level forecasts into actionable scenarios for procurement, R&D prioritization, go-to-market segmentation, and M&A targeting without disclosing the granular segment tables that subscribers will access in the full report.
Key market dynamics shaping 2026 strategy
Three structural forces are simultaneously accelerating product innovation and elevating supply risk across DC power supplies and electronic loads:
Worldwide Museum Software Market
- Technology-led demand: The move to higher power density and efficiency—driven by EV traction systems, power-hungry AI/data-center infrastructure, and advanced industrial automation—has escalated adoption of SiC MOSFETs, GaN topologies, and bidirectional/regenerative load architectures. These technology shifts favor suppliers that can integrate advanced semiconductors and thermal management into compact, high-reliability assemblies.
- Supply-chain stressors: Recent policy and market actions — such as expanded export controls on certain rare-earth magnets and U.S. measures addressing processed critical minerals — have created new sourcing constraints. Simultaneously, price increases for components like tantalum capacitors and MLCCs (reported increases in Q1 2026) and higher MOSFET/IGBT pricing and lead times are impacting BOM economics and schedule predictability for both OEMs and test-equipment manufacturers.
- Product differentiation and modularity: Demand for modular, software-defined power supplies and electronic loads (including 1U high-voltage platforms, rack-scalable regens, and VPX-aligned modules for defense/aerospace) is rising. Buyers prioritize systems that simplify integration, shorten validation cycles, and support firmware-driven feature upgrades.
Competitive landscape: capabilities and strategic postures
The market is characterized neither by monopoly nor fragmentation; incumbents and fast-follower specialists coexist. The competitive field includes legacy power-supply manufacturers, precision test vendors, and newer specialists focused on high-power, bidirectional, or high-density designs. Key strategic positions to note:
Electric Bike NMC Battery Market
- TDK-Lambda (TDK Corporation) — breadth and system depth: Leverages wide product breadth across programmable and standard DC supplies plus high-density DC-DC converters to serve industrial, semiconductor, and medical segments. Strength: global channel reach and R&D scale.
- Keysight Technologies — precision and test-ecosystem leadership: Focused on precision programmable supplies and advanced electronic loads for R&D and production test. Strength: integration with high-value ATE and measurement workflows used by semiconductor and power-device developers.
- Chroma ATE Inc. — regenerative and EV test focus: Emphasizes high-performance electronic loads and bidirectional/regenerative capabilities for EVs, batteries, and renewable systems. Strength: deep systems know-how for automated test and battery simulation.
- XP Power and Mean Well — differentiated product cost-performance plays: XP Power drives high-efficiency compact designs (including SiC/GaN adoption) for industrial/medical use, while Mean Well targets value-driven, wide-input products for automation and manufacturing customers.
- EA Elektro-Automatik, Advanced Energy, Magna-Power Electronics — power-dense and high-power system specialists: These firms compete on high-power programmable supplies, rack solutions, and thermal/packaging innovations suitable for automotive, industrial, and semiconductor fab testbeds.
- Module- and component-focused players (Vicor, Delta, Murata, Acopian, B&K Precision) — enabling blocks and quick-ship fills: Provide high-density DC-DC modules, converters, and benchtop/test units that feed larger system OEMs and contract manufacturers.
Recent product moves (for example, introductions of high-voltage 1U DC supplies, VPX-aligned DC/DC modules for aerospace, and new-generation programmable solutions targeted at automotive and new-energy testing) confirm the pace of innovation and vendors’ efforts to capture fast-growing adjacencies.
Strategic implications for 2026 corporate planning
Executives must translate the macro growth trajectory and the competitive snapshot into concrete actions. We highlight five priorities that should be in every 2026 plan for suppliers, OEMs, and strategic buyers:
- Design for supply resilience: Act now to qualify second- and third-source suppliers for key passives, power semiconductors, and magnetics. Consider inventory cushions for long-lead items and negotiate collaborative demand-forecasting arrangements with strategic suppliers.
- Targeted product bets: Allocate R&D spend to SiC/GaN-enabled power stages, compact thermal management, and bidirectional/regenerative features that are demonstrably monetizable in EV and data-center test markets. Prioritize software APIs and telemetry for higher-margin recurring revenue (service, calibration, firmware subscriptions).
- Commercial strategies that capture premium demand: For those with precision- or high-power capabilities, pursue vertical value plays (test-to-system bundles) and performance-based contracts where customers pay for delivered throughput or power-conversion efficiency gains.
- Regional and policy-aware sourcing: Map your supply chain exposure to export-control regimes and critical-mineral policies. Localized manufacturing and assembly, or at least buffered subassembly strategies, can mitigate regulatory and transport risks.
- M&A and partnership discipline: The market’s growth and mid-level concentration create opportunities to acquire complementary capabilities (e.g., regenerative load technology, high-voltage modules, or software/IP). Target deals that accelerate time-to-market for SiC/GaN and bidirectional systems rather than scale-only consolidations.
Operational metrics we recommend for 2026
To convert strategy into accountable execution, monitor a concise set of KPIs:
- Supplier risk index (weighted by lead-time and single-source exposure for top 20 components)
- R&D time-to-deploy for SiC/GaN-enabled platforms (months)
- Revenue mix from software/recurring services as a percent of product revenue
- Average order lead time and on-time delivery to key test/OEM customers
- Gross margin delta attributable to component cost shifts and hedging actions
What the full report delivers — practical content (preview)
PW Consulting’s full Worldwide DC Power Supplies and Electronic Power Loads Market report transforms the macro outlook into deployable insight: rigorous historical and forecast market sizing (2020–2032), segmentation by product family and end market, supply-chain exposure maps, vendor scorecards, detailed competitor profiles, and playbooks for procurement and product leadership. Importantly for strategists, the report contains scenario analyses that quantify the P&L and ROI implications of alternate supply-risk and technology-adoption paths. To honor the “trailer” principle of this briefing, segmented tables and the granular company-by-company quantitative rankings are reserved for subscribers and report purchasers.
How to use the report for 2026 decision cycles
- Board-level planning: Use the market-size trajectory and scenario outputs to stress-test capex and M&A assumptions during annual planning cycles.
- Product roadmap prioritization: Apply the supplier risk and component-cost scenarios to re-score product initiatives by time-to-market and margin resilience.
- Procurement negotiations: Leverage the supply-chain maps and price-trend analyses to structure multi-year supplier commitments, options, and inventory pooling agreements.
- Go-to-market refresh: Tailor channel and direct-sales motions based on the vendor scorecards and the identified high-growth subsegments (detailed in the subscriber report).
Final perspective and next steps
The DC power supplies and electronic power loads market offers a clear growth runway, but 2026 will be the year that separates strategic foresight from tactical reaction. Companies that proactively shore up supply chains, invest in SiC/GaN-enabled platforms, and convert product performance into recurring revenue streams will capture disproportionate upside as the market scales. Conversely, firms that wait for component prices and lead times to normalize risk margin erosion and lost design-wins.
PW Consulting’s full report provides the granular segmentation, vendor benchmarking, and scenario modeling necessary to operationalize the guidance above. For access to the complete dataset, supplier scorecards, and tailored advisory engagements to translate these findings into a 90–180 day execution plan, visit the PW Consulting research portal or contact our industry practice lead for a brief walk-through.
For detailed analysis of this topic, please visit the official page: Worldwide DC Power Supplies and Electronic Power Loads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Poly Ferric Chloride Market to Expand at a 5.51% CAGR
By pmarketresearch, 2026-08-12
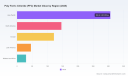
Worldwide Poly Ferric Chloride (PFC) Market: Strategic Outlook for 2026 Decision-Making
PW Consulting’s newest market study on the Worldwide Poly Ferric Chloride (PFC) market is designed as an operational playbook for executives preparing critical 2026 choices. The PFC market is no longer a niche chemicals story — it sits at the intersection of urban water infrastructure renewals, industrial decarbonization programs, and evolving global trade and regulatory regimes. Our report synthesizes a multi-year historical view (2020–2025) with a forward-looking forecast period (2026–2032) to convert ambiguity into executable options.
Worldwide Wireless Smart Lamp Market
Executive snapshot
Between 2020 and 2025 the global PFC market expanded from approximately USD 510 million to USD 650 million, reflecting steady demand growth through municipal and industrial channels and episodic supply-side interruptions. Looking forward, our base-case projection anticipates the market reaching roughly USD 945.5 million by 2032, underpinned by a compound annual growth rate (CAGR) of 5.51% across the 2026–2032 forecast window. These headline metrics frame the strategic choices companies will confront in 2026: invest, consolidate, diversify procurement, or reposition product portfolios.
Worldwide 1,2,6-Hexanetriol Market
Why this report matters for 2026 decisions
- Decision-ready intelligence: The report marries quantitative forecasting with qualitative scenario analysis so commercial leaders can translate a 5.5% mid-single-digit growth trajectory into revenue, margin, and capacity planning.
- Risk-to-reward mapping: We identify which near-term shocks (raw-material price volatility, trade actions, regulatory gating) are transient and which will reconfigure supply chains over the medium term.
- Competitive playbook: Practical vendor benchmarking and capability matrices enable procurement and product teams to prioritize partners and target competitive gaps that matter for 2026 procurement cycles.
Market trajectory and structural drivers
The overall growth profile is solid but non-linear. Growth through 2020–2025 reflected a mix of steady municipal capex and pockets of industrial demand; disruptions in 2022–2023 highlighted the sensitivity of PFC production to raw-material and utility inputs. On the supply side, players face concentrated cost drivers — hydrochloric acid and iron feedstocks — alongside energy and logistics constraints. On the demand side, rising urban population, stricter effluent limits, and expanded industrial water reuse programs are persistent tailwinds.
Worldwide Snap-off Knife Market
Crucially for 2026 planning, the market is moderately fragmented: the three-largest suppliers account for just over one-fifth of global production, while the five-largest are responsible for roughly one-third. That concentration profile implies meaningful room for regional producers to defend share, while also leaving strategic space for M&A and scale-driven cost reductions among larger players.
Key dynamics shaping 2026 strategy
- Raw-material volatility and procurement posture: Historical episodes in 2022–2023 showed hydrochloric acid and ferric chloride spot prices can spike materially following supply disruptions. Procurement teams should adopt multi-tier sourcing and proactively hedge exposure to feedstock cycles — spot-only procurement will be increasingly risky.
- Regulatory and trade headwinds: Regulatory regimes such as REACH require robust registration and data packages for imports, elevating the bar for non-local suppliers. Trade measures — including duties impacting certain import corridors — create incentives for near-shoring or tariff mitigation strategies.
- Product differentiation and R&D: New higher-purity and specialized PFC grades are emerging, aimed at advanced wastewater and reuse markets. Suppliers investing in application-specific formulations and stability/solubility improvements will command pricing premia in targeted industrial segments.
- Capex and capacity alignment: Recent capacity increases by established players have a two-fold strategic implication: they signal confidence in medium-term demand, but they also require disciplined offtake agreements and geographic distribution strategies to avoid cycle-driven oversupply.
Competitive landscape: what to watch in 2026
The PFC ecosystem combines multi-national incumbents with regional specialists. Our competitive analysis focuses on capability, route-to-market, product breadth, and strategic moves that directly affect 2026 positioning.
- Kemira Oyj (Helsinki): A global water-chemicals provider with integrated R&D and broad municipal and industrial channels. Kemira’s recent European capacity expansion signals a readiness to capture incremental municipal and industrial tenders. For customers, Kemira represents scale, regulatory compliance assurance, and advanced technical services.
- Feralco AB (Halmstad): A European iron-coagulant specialist with deep presence in drinking water and sludge management. Feralco’s strength is application-level expertise and regional regulatory know-how that eases market access for utilities subject to stringent safety standards.
- SNF Group (France): Renowned for polymer and coagulant technology, SNF’s complementary product set allows bundled offerings — a tactical advantage in large water-treatment projects where single-vendor coordination reduces integration risk.
- USALCO LLC (Baltimore): A North American player focused on potable and wastewater segments with domestic manufacturing advantages — particularly relevant where trade measures or logistics bottlenecks raise landed-costs of imports.
- Chinese suppliers (representative firms): Several leading Chinese producers continue to supply global markets at scale. Their competitiveness is shaped by feedstock access and export logistics; however, regulatory barriers and trade duties in certain jurisdictions alter their relative attractiveness for 2026 procurement decisions.
Two recent developments are illustrative: (1) an established European supplier expanded coagulant capacity in 2023, reflecting anticipated municipal project flows; (2) a Chinese producer launched a high-purity grade in 2022 targeted at advanced wastewater streams. These moves underscore a bifurcation: scale investments to serve high-volume municipal demand, and product innovation to serve high-margin, performance-sensitive industrial niches.
Core contents of the PW Consulting report (practical, actionable elements)
- Quantitative forecast model (2026–2032) with scenario toggles for raw-material shocks, tariff regimes, and regulatory tightening.
- Demand-by-use-case mapping (municipal, industrial reuse, paper & pulp, specialty) with adoption curves and addressable-market estimates by channel (note: the report contains the full segmentation tables and underlying assumptions).
- Supply-chain heat maps showing production nodes, logistics bottlenecks, and critical single-source exposures.
- Supplier capability matrices and commercial scorecards to support RFP design and supplier shortlisting.
- Regulatory compliance playbook (REACH, export controls, customs classifications) and a checklist for importers and in-region manufacturers.
- Procurement strategies — from fixed-price multi-year offtakes to indexed spot-mix — with modeled P&L impacts under the most likely 2026 scenarios.
- M&A and partnership roadmaps, including valuation heuristics and integration risks specific to PFC assets.
Strategic recommendations for executives preparing 2026 plans
- Design multi-scenario procurement contracts: Move away from pure spot exposure. Blend indexed contracts, capacity reservations, and local supply options to limit volatility in feedstock-driven cost lines.
- Prioritize product portfolio sophistication: Allocate R&D and commercial focus to differentiated grades that address reuse and stricter effluent standards. These segments show above-average willingness to pay for performance and technical support.
- Regionalize where tariffs or regulation raise entry costs: For markets subject to import duties or onerous registration regimes, near-shore manufacturing or licensed local partnerships will be less costly than attempting to compete on landed price alone.
- Use capacity signals as a sourcing lens: Track announced expansions and new-grade launches to anticipate pricing cycles. Where suppliers commit capex, secure offtake or co-development arrangements to lock favorable terms.
- Build a compliance-first GTM approach: Design product dossiers and safety data packages proactively; regulatory delays are a predictable cause of missed RFPs and lost market share in 2026.
- Evaluate M&A selectively for scale and tech: Given the market’s moderate fragmentation, targeted acquisitions can accelerate access to new geographies or proprietary formulations — but only when integration plans preserve technical capabilities and regulatory compliance.
How to use the report in boardroom and procurement cycles
Translate the report’s scenarios into the three documents that matter for 2026:
- Capital-expenditure justification — link forecast demand to capacity and payback models under both conservative and aggressive demand scenarios.
- Procurement policy — specify contract forms, indexation clauses, and supplier KPIs calibrated to feedstock risk sensitivity.
- Commercial strategy brief — align sales incentives and pricing templates to segments where product differentiation yields premium capture.
Access and next steps
This release is a strategic preview: it demonstrates the analytical depth and operational frameworks within PW Consulting’s full Worldwide PFC Market report. For procurement leaders, product strategists, and corporate development teams set to finalize 2026 plans, the full report contains the actionable segmentation, supplier benchmarking, and the downloadable model that operationalizes the scenarios summarized here. Those ready to convert insight into a concrete 2026 playbook should consult the complete study for the segment-level tables, modeled contract templates, and supplier scorecards.
PW Consulting continues to monitor raw-material and regulatory signals that will pivot near-term supply-cost dynamics. For bespoke advisory — including model customization, supplier diligence, or transaction support tied to the PFC market — our specialists are available to convert the research into transaction-ready outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Poly Ferric Chloride (PFC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Masonry Coating Industry Poised to Expand at a 4.82% CAGR Through 2032
By pmarketresearch, 2026-08-12
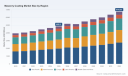
Worldwide Masonry Coating Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s forthcoming Worldwide Masonry Coating Market report (base year 2025) distills five years of historical performance (2020–2025) and delivers a forward-looking forecast through 2032. The market expanded from roughly USD 3.95 billion in 2020 to about USD 4.85 billion in 2025 and is modeled to grow to approximately USD 6.74 billion by 2032 at a 2026–2032 CAGR of 4.82%. This preview outlines the report’s strategic value for corporate decision‑makers in 2026 — highlighting the levers that will shape commercial outcomes while intentionally reserving the granular segment-level tables and exact share data for the full report.
Worldwide Web Security Software Market
Why this briefing matters for 2026 corporate decisions
-
Capital allocation: The market’s steady expansion and structural upticks in weatherproofing and sustainability demand call for disciplined investment in capacity, formulation R&D, and selective acquisitions that accelerate capability rather than increase commodity exposure.
Smart Elevator Automation System Market -
M&A and portfolio pruning: Fragmentation and pockets of technical differentiation create attractive tuck‑in opportunities. Our benchmarking shows consolidation benefits accrue to players that can convert product technology into specification wins.
Worldwide Porcelain Enamel Market -
Go‑to‑market and specification strategy: With architects, contractors and specification bodies increasingly prioritizing low‑VOC and climate‑resilient systems, specification capture is now a critical commercial competency — not just a product marketing exercise.
-
Supply chain and margin resilience: Input cost volatility demands active procurement strategies, indexation clauses, and backward integration options for strategic binders and additives.
Macro and structural dynamics — what’s driving growth to 2032
-
Market momentum and resilience: After recovering through 2020–2025, masonry coatings show a predictable growth trajectory into the late 2020s driven by renovation cycles, infrastructure maintenance, and resilience upgrades in both developed and emerging markets.
-
Input cost pressure: Construction material prices — including coatings inputs — rose materially in 2025 (Producer Price Index movements were ~6.2% across relevant categories). The practical consequence for manufacturers is a shorter pricing window to recover cost spikes and a heightened need for formula optimization.
-
Binder technology and formulation shifts: Acrylic resins remain the dominant binder technology globally, representing roughly the largest single share of binder demand. That persistence supports continued activity in acrylic-based systems, but it also concentrates risk where raw material dynamics change.
-
Sustainability and regulation: Rising demand for low‑VOC and sustainable protective coatings is creating differentiated value pools. Regulatory tightening and voluntary sustainability requirements are already accelerating demand for alternative chemistries, eco‑labeling, and third‑party certifications.
-
Fastest‑growing subsegments: Waterproofing and climate‑resilience related chemistries are outpacing other categories as owners prioritize protection of built assets against increasingly frequent weather extremes.
-
Cement‑based systems: Cement‑based paints and related systems remain important, underpinned by infrastructure buildouts and cost‑sensitive construction markets; the cement‑based paint vertical was valued in the low‑single‑billion USD range in 2025 and continues to be a key tactical play for volume‑oriented strategies.
What the PW Consulting report contains — practical, executable insight
This report is built as an operator’s toolkit rather than an academic exercise. Key deliverables include:
-
Proprietary market model: A demand‑side model that blends historical instalment, renovation cycles, construction starts, and specification adoption curves to produce regional and end‑use demand scenarios (base, downside, upside) through 2032.
-
Price and margin sensitivity analysis: SKU‑level margin waterfalls and elasticity matrices that let commercial teams model pass‑through and rebate strategies under inflationary or deflationary scenarios.
-
Supply‑risk heatmap: Supplier concentration, critical raw material mapping, and contingency levers for each major binder and additive class to support procurement playbooks.
-
Product strategy playbooks: Go‑to‑market templates for performance coatings, elastomeric systems, silicone technologies, and cementitious formulations — including formulation priorities, testing protocols, and specification capture tactics.
-
M&A screening engine: A qualitative and quantitative checklist to prioritize targets based on technology, recurring revenue, channel access, and integration complexity.
-
Field performance and life‑cycle cost models: Real‑world durability curves and TCO calculators to shape premium vs. commodity positioning and to inform warranty design.
-
Regulatory and sustainability matrix: Mapping of evolving low‑VOC thresholds, incoming product stewardship obligations, and voluntary ecolabels that affect specification and procurement behavior.
Competitive landscape — pockets of scale, wide scope for differentiation
The masonry coating landscape is characterized by a mix of global coatings leaders, specialized construction chemicals firms, and regional innovators. Market concentration metrics indicate a moderately fragmented competitive set (the largest three firms account for under one‑fifth of the market and the top five just over one‑quarter), which creates both acquisition runway for scale players and premium niches for technically differentiated suppliers.
-
The Sherwin‑Williams Company (Cleveland, USA): Strong in masonry primers and protective decorative systems; their strength is in channel coverage and specification relationships for building envelopes.
-
PPG Industries (Pittsburgh, USA): Following the strategic divestiture of their North American architectural business, PPG is sharpening focus on performance and protective coatings that include masonry applications — a move that concentrates resources on higher‑margin, specification‑driven opportunities.
-
AkzoNobel (Amsterdam, NL): The completion of a transformational merger in late 2025 significantly increases scale in performance and architectural coatings. Expect intensified competition around global account management and platform technologies.
-
RPM International (Euclid Chemical) and Sika: Both extend construction chemicals leadership into masonry systems via repair, waterproofing and polymer‑modified solutions — offering complementary routes to specification and project engineers.
-
BASF, Sto, Tnemec, Mapei and other technical players: These firms compete on formulation depth, system warranties and application performance for both new builds and restoration work.
-
Xypex and niche waterproofing specialists: Crystalline waterproofing and specialty dampproof technologies provide insulation from commoditization and create high‑value niches, especially in infrastructure and severe‑exposure applications.
Recent strategic moves to watch
-
AkzoNobel’s merger (Nov 2025) expands its performance coatings footprint — expect aggressive integration and product rationalization that will intensify competitive pressure in global accounts and cross‑sell channels.
-
PPG’s late‑2024 architectural divestiture refocuses their portfolio toward performance coatings where masonry applications intersect with industrial protective needs.
-
Capacity investments in upstream cement and related materials (for example, new white cement capacity announced by major regional players) are reshaping the supply equation for cement‑based coatings in some markets, lowering supply risk for players who pursue vertical collaboration.
Strategic playbook — five immediate actions for 2026
-
Prioritize waterproofing and low‑VOC systems in product roadmaps: Allocate R&D and pilot capacity to formulations that meet both climate resilience and regulatory trends; these command margin premium and specification preference.
-
Hedge and secure key binders: Lock strategic supply agreements or consider minority equity in critical additive suppliers to stabilize margins and protect lead times.
-
Invest in specification engineering: Build small, dedicated teams to work with architects, façade engineers and owners — specification movement is the primary channel to premium positioning.
-
Pursue targeted tuck‑ins: Look for specialty waterproofing, crystalline technology or restoration chemistry players that fill capability gaps and accelerate route‑to‑specification without heavy integration cost.
-
Embed lifecycle economics into sales motions: Equip sales with LCA/TCO calculators to move conversations from price per litre to cost per year of protection — a decisive advantage in renovation and infrastructure channels.
What we intentionally withhold in this preview
To preserve the commercial value of the full research, this preview omits the granular regional and application split tables, detailed company market share by segment, SKU‑level volume and price forecasts, and the full set of vendor financial benchmarks. Those datasets — which include precise segmental forecasts and vendor positioning matrices — are available in the complete PW Consulting report, along with downloadable models and customizable scenario inputs.
How to use the full report in 90 days
-
Week 1–2: Run the procurement heatmap against your supply contracts and identify two critical binders to hedge or source‑secure.
-
Week 3–6: Execute SKU rationalization using our margin waterfall and reprice or repackage two SKUs to improve gross margin by shifting customers to life‑cycle value propositions.
-
Week 7–12: Launch at least one commercial pilot (waterproofing or low‑VOC system) with specification partners using our field‑trial playbook and warranty template.
PW Consulting’s Worldwide Masonry Coating Market report is designed to equip executives and product leaders with the actionable intelligence required to make confident commercial and investment decisions in 2026. For access to the full dataset, segment tables, company shares and the scenario model, download the full report from PW Consulting’s research portal or contact our industry practice for a tailor‑made briefing.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Worldwide Masonry Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Industrial Control Automation Small PLC Market to Expand at 5.85% CAGR Through 2032, Report Finds
By pmarketresearch, 2026-08-12
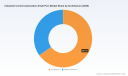
Worldwide Industrial Control Automation Small PLC Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Industrial Control Automation Small PLC market is designed for C-suite executives, product strategists, procurement leads, and systems integrators preparing capital, sourcing, and technology decisions in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, our analysis anchors on rigorous bottom-up modeling and primary validation. At a macro level, the small PLC market sits on a steady growth trajectory — with a compound annual growth rate of 5.85% and a 2025 market base of approximately USD 4.52 billion—projected to exceed USD 6.7 billion by 2032. This briefing summarizes the strategic value of the full report and highlights the practical levers leaders should prioritize in 2026, while reserving granular segment and share detail for subscribers and report purchasers.
LV Electric Panels Market
What the Report Delivers — Operationally Actionable Intelligence
-
Strategic market sizing and scenario planning: detailed, auditable forecasts built from installed-base tracking, vendor shipment data, and end-market consumption modeling. Scenarios include accelerated automation adoption, semiconductor supply shocks, and regulatory-driven retrofit cycles.
Worldwide Acrylic Binders Market -
Vendor benchmarking and playbooks: qualitative and quantitative scorecards across technical capability, security posture, channel strength, service footprint, and roadmap transparency. The report maps vendor advantages for machine builders, OEMs, and brownfield retrofit programs.
Worldwide Machine Learning in Education Market -
Procurement and sourcing checklist: an actionable RFP template, TCO model calibrated for small-PLC lifecycles (hardware, firmware maintenance, spare parts, and integration costs), and supplier negotiation levers for 2026 purchasing rounds.
-
Technical adoption guides: recommended architectures for compact and modular small-PLC deployments, integration patterns for IIoT/MES connectivity, and migration paths to enable motion control, safety, and energy management without wholesale system replacements.
-
Risk and compliance playbook: firmware lifecycle management, cybersecurity incident response protocols, and regulatory alignment guidance tailored to the latest advisories and energy-efficiency mandates.
-
Go-to-market motions: channel segmentation and partnership strategies for vendors and integrators targeting opportunities across discrete manufacturing, food & beverage, packaging, and machine building.
Why This Matters for 2026 Decisions
-
Capital allocation needs to be precise. With a predictable multi-year growth path and steady CAGR, 2026 is a pivotal year to prioritize investments in modular control platforms that scale with production requirements. Our TCO models show that choices made at procurement materially affect lifecycle costs and upgrade flexibility over a 7–10 year horizon.
-
Cybersecurity is now a procurement criterion. Following multiple advisories affecting small PLC lines, buyers must require secure boot, cryptographic firmware signing, encrypted communications, and defined update cadences as non-negotiables. The report provides contract language and technical checks to enforce that baseline.
-
Supply chain resilience influences vendor selection. Ongoing investments into semiconductor capacity globally and strategic government incentives are reducing risk, but near-term component tightness and geopolitical diversification will persist. Our scenarios offer hedging strategies—dual-sourcing prioritization, local stocking policies, and modular hardware designs that reduce dependence on single IC footprints.
-
Labor dynamics and sustainability mandates are accelerating adoption. Labor shortages and energy-efficiency regulations are increasing demand for small PLCs equipped with integrated motion control, power monitoring, and predictive maintenance capabilities—features that materially improve asset utilization and regulatory compliance.
Competitive Landscape — Who Matters and Why
The market combines entrenched global automation leaders, specialist OEMs, and nimble innovators. Buyers should evaluate suppliers along three vectors: platform breadth (hardware + software + services), openness (standards support and interoperability), and agility (product cadence and customization).
-
Global integrators and broad-portfolio leaders — companies such as Siemens, Rockwell Automation, Schneider Electric, Mitsubishi Electric and ABB — remain influential due to deep channel networks, broad product portfolios, and enterprise-grade support. Recent product refreshes and compact PLC introductions from these vendors underscore a push to simplify machine-level automation while embedding stronger connectivity and safety features.
-
PC-based and high-performance control specialists — Beckhoff and select European players — are advancing real-time control frameworks that appeal to high-precision machine builders seeking deterministic performance and richer HMI integration.
-
Cost-focused and integrated HMI vendors — Unitronics, Delta, and several Asia-based vendors — continue to compete on price-to-function value for OEMs and SMEs, often bundling PLC and HMI in compact form factors to reduce integration overhead.
-
Modular I/O and open-architecture proponents — WAGO, Phoenix Contact, and others — differentiate on interoperability and fieldbus/IIoT flexibility that simplifies brownfield upgrades.
Recent product developments validate these dynamics: a major vendor announced a next-generation intelligent logic controller in early 2026 with expanded function capacity and enhanced security; another expanded its micro-controller line in late 2025 emphasizing connectivity and simplified machine integration. Trade-show reveals in 2025 showcased AI-assist features and PC-based control evolution—indicating vendor roadmaps emphasize connectivity, security, and motion capabilities.
Strategic Playbook for 2026
-
Prioritize modularity and upgradeability over lowest-cost hardware. Select controllers with headroom for I/O expansion and software licensing that enables safe incremental upgrades.
-
Mandate security metrics in procurement: secure boot, signed firmware, role-based access, and demonstrable vulnerability disclosure policies.
-
Require standards compliance and open protocols (e.g., Ethernet-based industrial protocols and common fieldbuses) to future-proof integration with IIoT and MES layers.
-
Establish a two-tier sourcing strategy for critical components: maintain strategic spare inventories and pre-qualified second-source vendors to mitigate supply disruptions.
-
Incentivize vendors for sustainability: require energy-monitoring features and support for power-optimization profiles that align with corporate decarbonization targets.
-
Embed lifecycle clauses in contracts: defined firmware support windows, end-of-life notifications, and rights to security patches.
-
Leverage pilot programs: deploy compact PLC pilots to capture operational metrics (OEE uplift, labor-hours saved, and energy savings) and build internal business cases before scaling.
Risk Scenarios & Mitigation
-
Semiconductor supply shock: mitigate via design-for-component-flexibility, qualified alternates, and buffer inventory strategies.
-
Cybersecurity incident affecting field deployments: execute predefined incident response playbooks (network segmentation, device quarantine, forensic captures) and demand vendor cooperation clauses in SLAs.
-
Regulatory tightening on energy or emissions: fast-track retrofits with controllers that provide built-in power telemetry and demand-response capabilities.
-
Accelerated consolidation among vendors: maintain competitive RFQ processes and preserve migration paths to avoid lock-in risk.
How Leaders Use This Report in 2026
-
Board-level prioritization: translate market momentum and vendor roadmaps into capital allocation and M&A scouting for adjacent control technologies.
-
Procurement and supply chain: employ the report’s TCO and sourcing templates to standardize specifications across global plants and reduce fragmentation.
-
Product and R&D: align feature roadmaps with market demand for security, motion control, and IIoT readiness—using prioritized use-cases and quantified adoption curves from the report’s scenario analysis.
-
Systems integrators and OEMs: use vendor scorecards and channel maps to select partners with the right mix of product features, support footprint, and integration tools.
Next Steps — Where to Find the Full Intelligence
This briefing outlines the strategic contours of PW Consulting’s full Worldwide Industrial Control Automation Small PLC Market report. The comprehensive study includes detailed regional and vertical segmentation, vendor market shares and pricing benchmarks, product roadmaps, and downloadable procurement templates that are intentionally withheld from this preview to preserve the investigative value of the full deliverable.
For access to the complete dataset, vendor scorecards, and the downloadable playbooks and models that support rapid 2026 decision-making, please visit PW Consulting’s report page or contact our advisory team for a tailored briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Control Automation Small PLC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Thermometer Patch Market Poised for Rapid Expansion at a 10.45% CAGR, Driving Innovation Through 2032
By pmarketresearch, 2026-08-12
Worldwide Smart Thermometer Patch Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Smart Thermometer Patch Market — base year 2025, historical window 2020–2025 and forecast 2026–2032 — delivers focused strategic intelligence designed to inform board-level and business-unit decisions across product, regulatory, commercial and M&A agendas. The study synthesizes commercial telemetry, regulatory mapping and operator benchmarking to support high-consequence choices in 2026. At a headline level, the market has expanded from USD 495.2 Million in 2020 to USD 812.45 Million in 2025 and is projected to reach USD 1,629.12 Million by 2032, with a compound annual growth rate of 10.45% over the forecast period (USD, Million). These macro dynamics set the frame for urgent strategic questions we address in the report — and for which this release functions as a concise executive trailer.
Worldwide Disinfectants For Haemodialysis Market
Market trajectory and structural drivers
-
Acceleration in remote clinical monitoring and consumer health adoption: The convergence of telehealth reimbursement, post-pandemic remote care protocols and consumer demand for continuous, non-invasive vital-sign sensing has created a persistent tailwind for wearable temperature patches.
Worldwide Renewable Energy Technology Market -
Technology maturity and product bifurcation: The category is differentiating along technical vectors — single-use disposable patches optimized for short-duration clinical monitoring versus rechargeable reusable systems engineered for extended remote monitoring and chronic-care use cases. Connectivity modalities (Bluetooth, NFC, IoT), battery life and adhesive/tolerance performance have become key discriminators.
Common Mode Inductor Core Market -
Regulatory and standards environment: Smart thermometer patches sit within established medical-device frameworks. In the U.S., these devices are commonly regulated as Class II clinical electronic thermometers (21 CFR 880.2910, product code FLL), with 510(k) clearance required to demonstrate substantial equivalence for continuous axillary monitoring. Clinical accuracy expectations are anchored to standards such as ASTM E1112 (accuracy targets as fine as ±0.1°C), and in Europe MDR plus ISO 13485 quality systems are the baseline for market access. These regulatory constraints both raise barriers to entry and create a competitive advantage for incumbents with validated pathways.
-
Industry concentration: Competitive dynamics show moderate concentration with leading players accounting for a discernible share of commercialized value — a structure that supports both large-scale partnerships and targeted M&A to secure complementary capabilities (CR3 ~38.5%; CR5 ~52.3%).
What the PW Consulting report delivers — practical, transaction-ready outputs
-
Concise market model (2020–2032): bottom-up and top-down scenarios with sensitivity levers for price, adoption and reimbursement. The model is built for rapid what-if analysis to test investment cases and support valuation conversations.
-
Regulatory playbook: a stepwise clearance checklist (U.S., EU, select APAC jurisdictions) and clinical evidence matrices aligned to ASTM and MDR requirements — designed to accelerate 510(k) and CE/MDR submissions.
-
Product benchmarking and technology roadmaps: cross-vendor assessment on accuracy, connectivity, battery life, attachment systems and software ecosystems to inform specification trade-offs and product roadmaps.
-
Commercial go-to-market playbooks: segmented customer journeys for pediatric, remote clinical monitoring and consumer fertility tracking use cases, including channel strategies, pricing tactics and pilot designs.
-
Supply-chain and manufacturing diagnostics: supplier maps, capacity stress tests and inventory contingencies to de-risk scale-up and protect time-to-market.
-
M&A and partnership frameworks: diligence checklists, value-creation templates and integration risks tailored to acquirers targeting technology, regulatory clearances or geographic expansion.
-
Data governance and cybersecurity checklist: practical controls to make device-generated temperature data compliant, auditable and interoperable with EHR and RPM platforms.
Competitive landscape — what matters to strategists in 2026
-
Blue Spark Technologies (Westlake, OH, USA): A focused commercial challenger with an FDA-cleared disposable patch optimized for short-duration clinical and home fever monitoring. Their strength lies in a simple value proposition — disposable Bluetooth-enabled monitoring for early fever detection — and established hospital and caregiver channels that facilitate rapid pilots. Strategic consideration: transactional volume partnerships with hospital groups and pediatric networks can scale disposables quickly but margins are sensitive to adhesive and BOM costs.
-
VivaLNK Inc. (Campbell, CA; ops in China): A hybrid player offering reusable, rechargeable axillary patches with long battery life and IoT integration. Their multi-approval footprint (FDA, CE, NMPA) and platform orientation position them for enterprise RPM contracts. Strategic consideration: VivaLNK’s playbook underscores platform monetization and recurring revenue; competitors should evaluate trade-offs between device CAPEX and SaaS-based patient monitoring economics.
-
SteadySense GmbH (Austria): Differentiates on measurement precision and regulatory rigor (ISO 13485, MDR compliance). Their NFC-enabled approach and ±0.1°C accuracy cater to clinical applications demanding high fidelity. Strategic consideration: precision leadership enables premium clinical contracts (e.g., neonatal or perioperative monitoring), but requires investment in supply-chain quality and clinical validation studies.
-
iWEECARE Co., Ltd. (Taipei, Taiwan): Offers compact Bluetooth-enabled patches cleared for multiple indications (fever, fertility, RPM). Their product versatility and compact form factor are assets for consumer and mixed-use markets. Strategic consideration: multifunction devices can maximize unit economics across channels but necessitate clear messaging and segmented go-to-market pathways.
-
Guangdong Genial Technology Co., Ltd. (Zhaoqing, China): Recently secured FDA 510(k) clearance for a reusable Bluetooth-enabled wearable thermometer (October 2024). This regulatory milestone highlights China-origin manufacturers moving into regulated Western markets with competitive cost structures. Strategic consideration: western incumbents should monitor pricing pressure and consider partnership or contract-manufacturing strategies.
-
Helyxon Healthcare Solutions Pvt Ltd (India): Targets pediatric and hospital segments with a Bluetooth patch and app-based monitoring. Localized distribution and pricing are core advantages for high-volume, price-sensitive markets. Strategic consideration: emerging-market incumbents are an anchor for global players looking to optimize cost and reach.
Implications and recommended actions for 2026 corporate plans
-
Product portfolio strategy: Choose a clear position on disposable vs reusable economics. If targeting enterprise RPM, prioritize battery life, secure connectivity and clinical validation. If targeting acute-care pediatrics, ease-of-use and disposable operating models will matter more.
-
Regulatory prioritization: Pre-plan 510(k) and MDR pathways early. Invest in ASTM-compliant accuracy testing and ISO 13485 processes to shorten time-to-market and raise acquisition multiples.
-
Commercial approach: Pilot-to-scale playbooks are essential. Use short-term hospital pilots to prove clinical utility, then convert to subscription or device-as-a-service models for steady revenue.
-
Partnership and M&A playbooks: Target acquisitions that deliver either regulatory clearances or platform capabilities (IoT/cloud, analytics). Given the market’s moderate concentration, bolt-on deals can accelerate access to hospital networks or consumer channels.
-
Supply-chain resilience: Diversify adhesive/patch-material suppliers and validate secondary contract manufacturers in low-cost geographies to protect margins during volume ramp.
-
Data and interoperability: Prioritize standards-based APIs and EHR integrations to enable clinical workflows and justify enterprise pricing.
-
Pilot design and evidence generation: Plan randomized or controlled real-world evaluation studies that map temperature sensing data to clinically meaningful endpoints (early sepsis alerts, remote triage decisions, fertility cycle confirmation) to build payer and provider trust.
90-day executive playbook to mobilize on the opportunity
-
Days 0–30: Use the report’s scenario model to stress-test revenue and cost assumptions for targeted launches; map regulatory gaps and begin ASTM/MDR test procurement.
-
Days 30–60: Initiate prioritized pilots with two clinical partners (one acute, one RPM). Negotiate data-sharing agreements and define endpoints for clinical evidence generation.
-
Days 60–90: Lock down supply-chain contingencies and finalize a commercialization partnership (distribution or platform OEM). Begin regulatory submissions if product is ready; otherwise, finalize design freeze and clinical protocol.
Conclusion — why this report matters for 2026 decisions
Temperature-sensing patches are moving from niche adjuncts to platforms that intersect clinical care pathways, consumer health and telehealth infrastructure. PW Consulting’s market model and playbooks translate that transition into actionable decisions: where to allocate R&D budgets, which regulatory investments buy the most optionality, how to design pilots that convert into contracts, and how to size M&A that meaningfully changes competitive position. This release highlights the strategic logic and competitive map — and the full report provides the segmented datasets, regional and application breakdowns, and downloadable financial model necessary to finalize 2026 plans. For executives preparing capital allocation, product launches or M&A in 2026, the report is designed to be the operational foundation for those choices.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Thermometer Patch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Zero Gravity Bed Market to Top USD 3,975.76 Million by 2032, Growing at an 11.85% CAGR
By pmarketresearch, 2026-08-12
Worldwide Smart Zero Gravity Bed Market — Strategic Preview for 2026: Why C-Suites and Investors Must Recalibrate Now
PW Consulting’s latest market study on the Worldwide Smart Zero Gravity Bed Market (base year 2025; forecast 2026–2032) delivers a focused strategic lens for leadership teams preparing decisions in 2026. With the market expanding at a compound annual growth rate (CAGR) of 11.85% through the forecast horizon, the sector has moved decisively from niche therapeutic applications toward mainstream consumer and institutional adoption. Our analysis shows a market that roughly doubled in scale over the recent five-year window and is now positioned to approach a fourfold expansion by 2032 — a structural shift demanding proactive product, go-to-market, and regulatory strategies.
Worldwide Smartphone Screens Market
Why this preview matters for 2026 decision cycles
-
Momentum is predictable but not uniform: The industry’s average growth trajectory (CAGR 11.85%) masks pockets of rapid innovation and induced demand driven by integrated smart features, telehealth-enabled care pathways, and reimbursement clarity. Companies that align investments with these inflection points will capture disproportionate share.
Worldwide Email List Cleaning Service Market -
Concentration offers both threat and opportunity: Market concentration metrics indicate a moderately consolidated sector — the top three players control a meaningful but non-dominant share, and the top five widen that influence. This creates an environment where scale advantages coexist with white-space opportunities for focused entrants and specialized OEMs.
Battery Operated Mobile Power Market -
Regulatory and reimbursement dynamics are now operational drivers: Updated durable medical equipment (DME) policies and coverage rules require manufacturers and channel partners to embed compliance and clinical evidence into product design and commercial models. Execution on these fronts is becoming as important as product ergonomics.
Market trajectory at a glance (strategic highlights)
Our top-line market sizing traces the transition from early adoption to structural growth. Measured against our 2025 baseline, the market grew meaningfully from the 2023 vintage and is forecast to nearly double by the end of the 2026–2032 period. This expansion is being powered by three concurrent forces: technology convergence (embedded sensors, AI-driven sleep management, and connected actuation), shifting care delivery models (home-first rehabilitation and remote monitoring), and consumerization of sleep health. For 2026 strategic planning, executives should treat these forces as investment priorities rather than speculative trends.
Actionable intelligence embedded in the report
-
Scenario-based revenue models: Our report supplies base, upside, and downside scenarios to stress-test capital allocation, pricing experiments, and channel investments. These models incorporate sensitivity to reimbursement policy shifts and component supply volatility.
-
Go-to-market playbooks: Detailed route-to-market matrices for OEMs, contract manufacturers, and retailers — including recommendations on channel mixes, partnership archetypes, and margin structures tailored to different strategic objectives (premium brand growth, volume play, clinical/evidence-led sales).
-
Product feature roadmap templates: Prioritized product requirements for three strategic archetypes (clinical-first, premium consumer, and cost-optimized volume) that map engineering effort to measurable commercial outcomes.
-
Regulatory & reimbursement mapping: A practical compliance checklist and stakeholder map referencing recent CMS guidance on hospital beds as DME (including HCPCS considerations), and operational implications for ordering, documentation, and supplier accreditation.
-
Supply chain and cost benchmarking: Component sourcing strategies, outsourcing thresholds, and contingency planning for actuator and electronics constraints that can compress margins if unaddressed.
-
M&A and partnership playbook: Deal-screening criteria, integration risk matrices, and valuation multipliers calibrated to current market dynamics and consolidation patterns.
Competitive landscape — what the leading players reveal
Our competitive analysis focuses on firms that illustrate the strategic archetypes shaping the market. Each company’s positioning offers lessons for incumbents and newcomers alike.
-
SonderCare (London, Ontario) — Represents the clinical-first archetype: premium home hospital solutions emphasizing therapeutic positioning (including zero gravity), catering to long-term care and recovery settings. Their playbook demonstrates how clinical credibility and specialized features enable higher ASPs and clinical channel access, but also require persistent evidence generation and service capabilities.
-
Ergomotion (Santa Barbara, CA) — The volume-engineering and retail-supply leader: a global supplier of adjustable bases with deep relationships across mattress OEMs and mass retail channels. Their recent 20th anniversary and showroom investments underscore the value of brand-agnostic, scalable manufacturing and retailer enablement as routes to durable distribution advantages.
-
Leggett & Platt (U.S. adjustable beds division) — Industrial-scale OEM with an emphasis on modular platforms, programmable presets, and integration-ready architectures. Their scale plays to supplier leverage and channel breadth; the strategic takeaway is that modularity plus robust distribution can lock in preferred supplier status with large retailers and healthcare systems.
-
Tempur-Pedic — Premium consumer integration leader: combines advanced bases (smart features, snore response, Sleeptracker-AI) with a premium mattress franchise. Their success highlights the commercial premium available to companies that fuse sleep data platforms with ergonomics and an elevated retail experience.
-
Hebei Chibang Medical Equipment — A manufacturing-led competitor focused on hospital and post-operative segments, demonstrating how cost-efficient electronics integration and regulatory alignment can win institutional tenders in emerging markets.
-
Zero-G Beds (India) — Regional OEM and homecare specialist, illustrating that localized manufacturing and medical-grade features can create defensible positions in large, underserved domestic markets.
These profiles point to three critical competitive playbooks: platform scale + channel depth; clinical differentiation + service; and regional manufacturing + regulatory fit. Winning companies will combine two or more of these playbooks with clear investment sequencing.
Regulatory and reimbursement dynamics — from noise to strategic signal
-
Coverage pathways: Medicare Part B continues to cover hospital beds as durable medical equipment when clinical criteria are met, with HCPCS codes and documentation requirements driving supplier compliance and billing workflows. Manufacturers that design traceable clinical positioning features and provider-ready documentation lower adoption friction.
-
Medical necessity and ordering: Recent CMS clarification emphasizes face-to-face practitioner evaluation and demonstrable inability to meet positioning needs with ordinary bedding. This increases the importance of clinician education, point-of-care evidence kits, and training programs for channel partners.
-
Market segment drivers: Product designs addressing elderly care, post-operative recovery, and long-term care show the strongest alignment with reimbursement criteria. However, consumer demand for sleep health and home wellness expands total addressable market beyond purely reimbursable channels.
Strategic recommendations for 2026 planning
-
Invest in modular architectures now: Prioritize engineering that separates clinical modules (actuation, pressure management, articulating frames) from consumer-smart layers (sensors, AI). This enables faster regulatory iterations and multiple go-to-market plays without full redesigns.
-
Embed evidence generation into product development: Short, targeted clinical studies that demonstrate positioning benefits (pressure redistribution, circulation) will accelerate adoption in clinical channels and strengthen reimbursement claims.
-
Forge distribution partnerships with clear roles: Retailers, DME suppliers, and health systems require differentiated commercial models. Consider hybrid partnerships that combine retail reach with clinical referral programs and bundled service offerings.
-
Mitigate supply risk through dual-sourcing and design for substitution: Actuator and electronics availability are strategic chokepoints; design choices that allow supplier substitution without losing feature parity preserve margin and launch timelines.
-
Price for value, not cost: As smart features proliferate, pricing should reflect measured clinical or quality-of-life outcomes. Demonstrable benefits justify premium positioning while enabling participation in reimbursable channels where appropriate.
-
Evaluate M&A for capability infusion: Bolt-on deals that bring telehealth platforms, clinical evidence pipelines, or regional manufacturing can be more accretive than broad horizontal consolidation at current valuation multiples.
What the full report delivers (operational content)
PW Consulting’s comprehensive report contains detailed methodology notes, quarterly-trended market sizing (historical 2020–2025 and forecast 2026–2032), supplier benchmarking, price and cost models, channel maps, regulatory checklists, and prioritized strategic initiatives for each corporate archetype. It includes scenario-based financial models, sensitivity analysis for component costs and reimbursement shifts, and an M&A compendium with transaction rationale and integration risk scoring. The document is intentionally dense with executable checklists and templates designed for rapid adoption by product, commercial, and corporate development teams.
Next steps — for executives who need to act in 2026
-
Use the report’s scenario suite to stress-test your 2026 budget and roadmap against reimbursement tightening and component price swings.
-
Schedule a strategy workshop with PW Consulting to translate the playbooks into a 90–180 day implementation plan (product, regulatory, and channel milestones).
-
Engage our M&A advisory to validate inorganic options mapped to your strategic gaps — whether capability, geographic presence, or platform acceleration.
PW Consulting’s preview establishes the strategic contours you need to decide in 2026: the market is large, growing at a sustained double-digit CAGR, and split across distinct competitive archetypes. The levers of success are now well understood — but their execution requires discipline across product architecture, clinical evidence, channel orchestration, and supply chain resilience.
Learn more
This release serves as a concise strategic preview. For full market tables, detailed segment analysis, competitor scorecards, and the operational playbooks described above, access the complete Worldwide Smart Zero Gravity Bed Market report on the PW Consulting portal or contact our advisory desk to arrange a briefing tailored to your organization’s strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Zero Gravity Bed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com